Tuesday, July 20, 2010

personal finance books

Kelley wrote recently with the sort of dilemma I get asked about all of the time: Is it better to invest or to prepay a mortgage? We’ve covered this topic in the distant past, but it’s time to review the debate for current readers. First, let’s look at Kelley’s e-mail:


My husband and I are on the right track. At age 25, our only debt lies in our home mortgage. We have the six-month emergency fund in place, I currently meet the 3% 401(k) match offered by my employer, and I started a Roth IRA for myself and my husband last year. I started each Roth IRA with $4,000.


My financial advisor recommended for us to max out each of our Roth IRAs each year. My husband disagrees. He thinks paying off the house is a bigger priority. Starting this year, we’ve made an extra payment on our house each month. If we continue doing this, we can have our house paid off in nine years rather than 30 years. However, we can’t do both.


Currently we’ve decided to throw $1,000 into each Roth each year until the house is paid off. Is this the wise decision? Or is it better to put more toward the Roth IRA and less toward the house?


I understand either option is good because I’m saving money. I’m just curious of which route would be wiser.


Kelley’s right: Both of these options are good. This is like choosing between an apple and an orange. Both taste good, and they’re good for you &madsh; but is one better for you in the long run?


What the experts say

Three years ago, when we last covered this topic (holy cats! — where has the time gone?), I collected the following roundup of advice from personal-finance books:


  • Ric Edleman (Ordinary People, Extraordinary Wealth): Never own your home outright. Instead, get a big 30-year mortgage and never pay it off — regardless of your age and income. “Every time you send an extra $100 to your mortgage company, you deny yourself the opportunity to invest that $100 somewhere else.”


  • Suze Orman (The Laws of Money): Invest in the known before the unknown. Paying off your mortgage offers a guaranteed return on investment. “You cannot live in a tax return. You cannot live in a stock certificate. You live in your home.”


  • Elizabeth Warren (All Your Worth): Save 20% of your income. Use 10% for retirement savings, 5% to accelerate your mortgage, and 5% to save for future dreams. “Paying off your home also does something many financial planners neglect to mention: It gives you freedom. Once that mortgage is gone, just imagine all the freedom in your wallet.”


  • Dave Ramsey (The Total Money Makeover): Prepay your mortgage if you can, but only after you’ve saved an emergency fund, and only if you’re putting at least 15% of your income toward retirement. Don’t use a program designed by a broker; use your own self-discipline.


  • Dominguez and Robin (Your Money or Your Life): “Pay off your mortgage as quickly as possible.” This book, too, was written when interest rates were higher. Also, the authors emphasize frugality over investing.


Financial authors don’t agree on this subject. Maybe the personal finance gurus writing for the web can clear things up?


  • Liz Pulliam Weston at MSN Money: Don’t rush to pay off the mortgage. “You’ve got better things to do with your money, like saving for retirement, building an emergency cushion or even living it up a little.”


  • Walter Updegrave at CNN Money: If you’ve funded your retirement, and if it will make you happy, then pay down the mortgage. Otherwise, it makes more sense to invest.


  • Laura Rowley at Yahoo! Finance: Using very conservative figures, investing instead of prepaying the mortgage yields an extra $400 per year. If you feel compelled to pay down your mortgage, do it. But realize you’re paying a price to do so. (She offers more details at her blog, as well as tips on how to estimate the investment return you need to earn to make it worthwhile.)


  • Bankrate: Pay down your mortgage if your investments would be conservative. Invest if you’re planning to do so for the long term.


  • USA Today: It depends on your income, your monthly expenses, your risk tolerance, and your desire to own your home free and clear.


  • Kiplinger’s: Invest unless you’re near retirement


  • The Dollar Stretcher: Mathematically, it makes more sense to invest, but it all depends on your risk tolerance.


  • My fellow pfbloggers at Bargaineering and Million Dollar Journey recommend that a person do a little of both: pay down the mortgage some and invest some. Free Money Finance says: “If you have the discipline to save/invest the money you would be using to pay off the mortgage, it’s likely that saving/investing is the better option. But if you’re more the “average” person out there managing your money, I still believe it’s a better option to pre-pay your mortgage.”


The Rowley article offers some interesting background to this debate:


Why do so many people choose to put extra money into a mortgage when other options would likely increase their wealth? “This is really remnant of Depression mentality that has persisted from generation to generation,” says [one expert]. At the time, most mortgages had one- to five-year terms, with a lump sum payment due at the end.


“Any shock to income meant you couldn’t afford your payment — mortgages were much more susceptible to economic uncertainty,” [the expert says], and roughly one-quarter of Americans were unemployed during the Great Depression. “It’s fine to pay down your mortgage if it gives you peace of mind, but you should recognize what that peace of mind costs.”


If you’re facing a similar decision, you may find this calculator useful: prepaying your mortgage vs. investing.


The bottom line

My conclusion in 2007 (and the one I still hold today) is that unless your mortgage rate is very high, it makes more sense mathematically to invest your money. But most gurus agree that psychologically, you should do what works for you. If paying off your mortgage would take a weight off your shoulders, then pay off your mortgage. Sure, you might be losing a bit in the long-term, but you’re still making a smart choice. As I said earlier, it’s like choosing between an apple and an orange. One may be better for you, but they’re both good.


Ultimately, I kind of like the choice that Kelley and her husband have made. They’re prepaying their mortgage and putting some toward retirement. But enough of what I think. Kelley really wants to know what you think.


Which option is better? Should she and her husband be pumping as much as possible into their Roth IRAs? Or should they be paying down their mortgage as quickly as they can? Have you been faced with a similar dilemma in the past? What did you choose to do? And would you make the same choice again?


  • Colbert King:

    Family, marriage and the contribution of fathers come together as topics for reflection on Father's Day. So I'd like to know why Barack Obama, a husband and a father in a family structure that encompasses bonds deemed essential to our society, is constantly and savagely attacked by conservative leaders whose personal circumstances undermine the family values they espouse?


    Consider Obama: Raised by a single mother in a middle-class family where hard work and education were watchwords, Obama graduated from two of the top schools in the country, Columbia University and Harvard Law School. His legal scholarship was recognized when he became the first African American president of the Harvard Law Review. He married and, equally important, has stayed married to Michelle Robinson, a Princeton graduate and Harvard Law alumna. He lives with his wife, two children and his mother-in-law. Obama: constitutional law professor, civil rights lawyer, state legislator, U.S. senator, 44th U.S. president, family man.


    Now let's turn to Obama's foremost critics: Rush Hudson Limbaugh III, Newton Leroy Gingrich and Sarah Palin.


  • Eighty-five percent of Swedish fathers take parental leave. It's expected, both by employers and society as a whole.


    In this land of Viking lore, men are at the heart of the gender-equality debate. The ponytailed center-right finance minister calls himself a feminist, ads for cleaning products rarely feature women as homemakers, and preschools vet books for gender stereotypes in animal characters. For nearly four decades, governments of all political hues have legislated to give women equal rights at work — and men equal rights at home.


    Swedish mothers still take more time off with children — almost four times as much. And some who thought they wanted their men to help raise baby now find themselves coveting more time at home.


    But laws reserving at least two months of the generously paid, 13-month parental leave exclusively for fathers — a quota that could well double after the September election — have set off profound social change.


  • In 2002, a telecommunications engineer with dual Canadian/Syrian citizenship was seized from JFK airport, held in solitary confinement for two weeks without adequate access to an attorney, then sent to Syria, where he was imprisoned for a year and tortured. Then, he was released back to Canada. Jeralyn explains that although the Supreme Court denied cert in his civil lawsuit against U.S. officials, at least someone official is investigating. The Royal Canadian Mounted Police.


  • Blackwater is awarded a new contract -- under another name, of course -- to guard U.S. consulates in Afghanistan. --Susan Gardner

  • Republicans just can't help revealing their unhinged extremism, and no matter how many times they later backtrack, they are what they are.


    The Republican nominee for a northern New Mexico congressional seat suggested during a radio interview that the United States could place land mines along the Mexican border to secure the international boundary.


    Asked Monday to clarify, Tom Mullins emphasized that he does not advocate doing so.


    He was just making conversation. Or something.


  • Dahlia Lithwick:


    Almost two weeks ago, former Supreme Court Justice David Souter gave the commencement speech at Harvard, a speech that's been variously described by some of my favorite legal writers as a denunciation of "originalism," a defense of "living constitutionalism," and a suggestion that "judicial activism" is a game both liberals and conservatives can play. But the striking aspect of Souter's remarkable speech is that it rejected virtually all of these easy ideological labels and addressed itself to two much simpler questions: Is the meaning of the Constitution clear? And is the task of divining that meaning easy? These incisive questions themselves beg an even more pressing constitutional question: Why must justices first leave the bench before they can speak seriously about the importance of the court?


  • Science Daily:


    Advances in high-yield agriculture over the latter part of the 20th century have prevented massive amounts of greenhouse gases from entering the atmosphere -- the equivalent of 590 billion metric tons of carbon dioxide -- according to a new study led by two Stanford Earth scientists.


  • Andrew Lawler, in Science Magazine:


    After decades of taboo and controversy, Pacific Rim archaeologists are finding new evidence that Polynesians reached South America before Europeans did, voyaging across the world's largest ocean around 1200 C.E.


  • Cynthia Tucker's reaction to President Obama's energy speech was concise and pointed.


  • Diego Valle makes a comprehensive analysis of the Drug War in Mexico. Suffice to say that the present strategy isn't working. If you don't have a lot of time, just scroll down to his conclusions.


  • Europe's recession might bring down Germany's Merkel government, and is leading to a rise in xenophobia and racism.


  • Markos linked this, last week, but it deserves an encore. After taking apart the canard that Social Security is going broke, digby ends with this gem:


    Any deficit scold who doesn't put reducing health care costs at the very top of the agenda is just a demagogic crank doing the dirty work for the aristocratic overlords.


  • Defense Secretary Robert Gates claims Iran could launch hundreds of missiles into Europe. At least he didn't claim it could be done in 45 minutes.


  • Pretend you're surprised:


    Recent setbacks in Afghanistan have intensified debate over the wisdom of the Obama administration's plan to begin withdrawing U.S. military forces next summer and highlighted reservations among military commanders over a rigid timeline.


    At a Senate hearing Tuesday, Gen. David H. Petraeus, who oversees U.S. forces in the Mideast and Afghanistan, offered "qualified" support for President Obama's plan to begin withdrawing troops in July 2011.


    You have to admire the logic. The worse things get, the longer we have to stay.


internet marketing course


"Be All You Can Be" is not just a slogan for military recruiters, but a challenge we can all embrace. Below are mini-reviews for ten books that can contribute to a better you. Not just "self-help" books, they are books about travel, personal finance, mental health, as well as several thought-provoking biographies and books about achieving career goals. All are readily available for purchase or library borrowing and highly recommended for a broad readership across genders and age groups.

Staying Positive

Always Looking Up: The Adventures of an Incurable Optimist by Michael J. Fox, Hyperion Books, 2009.

This autobiography of the beloved television and film actor centers on the ten years since he left Spin City due to increased symptoms of Parkinson's disease. It is inspiring but never maudlin, factual but also gives a lot of insight into the way Fox has coped emotionally and even grown in the past decade. It is well worth reading even if you are not a hard core Michael J. Fox fan and never saw Back to the Future I, II, or III.

One Less Thing to Worry About: Uncommon Wisdom for Coping with Common Anxieties by Jerilyn Ross with Robin Cantor-Cooke, Ballantine Books, 2009.

Jerilyn Ross is a practicing psychotherapist and an expert on anxiety. In this book she addresses some anxieties experienced by many and provides useful and engaging case studies. This book can help those who feel that their anxiety is not well-controlled, whether or not they have an official "anxiety disorder." This book is neither super-clinical and jargon laden, nor is it superficial and sensationalistic. It falls in the middle realm of practical, readable material about an important health-related topic.

Career

The Presentation Secrets of Steve Jobs: How to be Insanely Great in Front of Any Audience by Carmine Gallo, McGraw-Hill, 2010.

Although Steve Jobs expounding on Apple products at a MacWorld Expo is front and center on the cover of this book, the book was not endorsed or approved by him. Instead, it consists of Ms. Gallo parsing, analyzing, and learning from the techniques he has used in his well-known presentations to industry insiders and Apple faithful. Jobs is an interesting case study, since he is so well known. Although he does not have the classic salesperson manner, he may be the computer geeks' salesman of choice. There are lessons we can learn from Jobs as a presenter and from this book.

Your Next Move: The Leader's Guide to Navigating Major Career Transitions by Michael D. Watkins, Harvard Business Press, 2009.

This book is a follow-on to Watkins' successful The First 90 Days, which gave advice to managers transitioning into a new organization. In Your Next Move, he explores other scenarios, including promotion, turning a business in crisis around, and making an international move. Anyone who holds a management role in a large organization or aspires to do so in the future will find this book interesting and perhaps enlightening.

Global Perspective

Three Cups of Tea: One Man's Mission to Promote Peace...One School at a Time by Greg Mortenson and David Oliver Relin, Viking hardcover 2006, Penguin paperback, 2007.

Greg Mortenson is a large quirky American guy who morphed from a nurse cum recreational mountain climber into a global humanitarian raising money to build schools where there were none. His work in the mountainous rural regions of Pakistan and Afghanistan is chronicled in this bestselling book by journalist David Relin. I heard Relin speak about writing this book and left very impressed by the accomplishments of Mortenson despite his feet of clay.

1000 Places to See Before You Die by Patricia Schultz, Workman Publishing Company, 2003

This book is a modern classic and was number one on the bestseller lists; its clever title has given rise to many spinoffs written by other authors, including 1000 Recordings to Hear Before You Die and 1000 Historical Sites to See Before You Die. Schultz spent seven years researching and writing this ambitious book. In the introduction she explained why:

"With travel, our minds become more curious, our hearts more powerful, and our spirits more joyous. And once the mind is stretched like that, it can never return to its original state."

In 2007, Patricia Schultz published a version of the book limited to sites in the U.S.A. and Canada.

Your Stuff

The Get Organized Answer Book: Practical Solutions for 275 Questions on Conquering Clutter, Sorting Stuff, and Finding More Time and Energy by Jamie Novak, Sourcebooks Inc., 2009.

Jamie Novak is an organizer who has been featured on the television program Mission Organization—the more sedate version of Clean House. As a person who needs a lot of organizing, I have a whole collection of books on this topic. I like the Answer Book because it is well organized! (Imagine that: a book about organization that is well organized!) The Q and A format makes it easy to hone in on topics of interest.

Cool Green Stuff: A Guide to Finding Great Recycled, Sustainable, Renewable Objects You Will Love by Dave Evans, Crown Publishing Group, October 2007

This book will fascinate readers who think shoes made of recycled seatbelts, chandeliers made of party favors from the millennium celebrations, and jewelry made from vinyl records are cool. It contains photographs and website addresses for these treasures. Reviewers describe it as fun, creative, and very entertaining to read or leaf through—a small coffee table book. In fact it includes a coffee table made of coffee grounds!

Personal Finance

The Number: A Completely Different Way to Think About the Rest of Your Life, by Lee Eisenberg, Free Press, 2006.

Lee Eisenberg muses on "the number"—that is, the amount of money one needs to have saved in order to retire, or semi-retire. For many years Editor in Chief of Esquire magazine, Eisenberg left the hustle and bustle of New York for a calmer but less lucrative existence elsewhere. He uses his own struggle with the concepts of retirement and financial security as a way of exploring the concepts universally. It is written in a lively, literate style and very thought-provoking.

Making the Most of Your Money Now by Jane Bryant Quinn, Simon and Schuster, hardcopy, revised 2009.

I have had great respect for Jane Bryant Quinn as a sensible and comprehensive money guru for decades. However, her books of the 1980's needed updating for all the economic upheavals since. She has fully revised her near-encylopedic money management manual (1,264 pages) and published a new version as of December 2009. Her book is organized topically so you can dip in and read about whatever you need at the time—the basics of life insurance, paying for college, investing, etc. Her book is not flashy, not gimmicky, not pitched to the wealthy or the high rollers. It is good solid information and advice for most people and written in a clear, understandable style.

Conclusion

This list of ten suggested books to make a better you is far from exhaustive. Depending upon the areas in which you seek enrichment, growth, or improvement, you may find additional books or more specialized books appropriate. But this is a good starter set for almost anyone of a mind to be all you can be.

Sources:

Books cited above
Personal opinion and experience


penis enlargement

<b>News</b> Roundup: Doris Roberts Heads to &#39;The Middle,&#39; Scott Porter <b>...</b>

Doris Roberts and Patricia Heaton are going to do battle once more, but this time it'll be on 'The Middle.' The two famously sparred often.

Project Milo back on Xbox 360 <b>News</b> - Page 1 | Eurogamer.net

Read our Xbox 360 news of Project Milo back on. ... Latest Features. Milo & Kate Interview . Milo & Kate Hands On . Milo & Kate Interview . Latest Videos. E3: Project Natal - Milo demo 2 June, 2009. Latest News ...

EA announces Alice: Madness Returns <b>News</b> - Page 1 | Eurogamer.net

Read our news of EA announces Alice: Madness Returns.


how to lose weight fast


Monday, July 19, 2010

personal finance and budgeting


What a fantastic basic concept.

Hitler lost the second world war because he attacked Russia too soon. udervise ve vood all be speeking Deutsch now.


We employed the alternative massively effective budgetting tool.


Be a self employed Engineer for 15 years with take home pay of £50K a year and spend it all (and more besides, because ‘I want one of those NOW’) because ‘my jobs safe’.


Watch as the banks destroy the worlds finances.


Suddenly realise that over 90% of British industry is ultimately owned by Japanese investment banks, who suddenly have no money to fulfill their legal obligations to complete legislation driven improvment projects.


Watch as my £50K a year take home falls to ZERO.


Start a brand new business with Kleeneze (sorry not available in the USA) Which although it’s building really well is , after all, a business and needs time.


Suddenly HAVE to live on £18K a year GROSS.


Best Motivation for re-inventing your budget that anyone can have LOL.


We used to spend about £1,000 a month on groceries, now we spend around £300 a month, AND we eat more healthily.


Fortunately the finance on my car ended a month after our income disappeared saving us £375 a month.


We’ve sold my wifes’ car (THAT hurt) it was a really nice car, but it was costing us £489 a month in finance.


We’ve moved to a cheaper house saving us £400 a month in rent.


We’ve cancelled everything that wasn’t absolutely essential - including SKY and the TV license (It’s true, you don’t die if you turn the telly off!)


We still have creditors who we’re negotiating reduced payments and frozen interest with, but basically we are starting again from scratch.

We won’t fall into the credit trap again

Certainly not in the next six years or more ‘cos no-one in their right mind will give us credit now anyway!!


The one thing that keeps coming back to me though is


WHY aren’t our schools teaching kids how to budget? It’s a thousand times more important than even the basics.


Who cares if you can’t spell budgit if you can make one and stick to it.


It CAN’T be one of the things that are left to parents because nobody ever taught us!


Back to subject,

Your article is brilliant and if it helps one person (which I’m sure it already has) to get out or stay out of debt then you’ve done a service to humanity.


Keep it up &

we’ll see you

OVER the top


In 2006, recent Harvard grad Alexa von Tobel was headed for a job at Morgan Stanley. But though she would soon be managing the bank’s investments, she realized she didn’t know the first thing about her own finances. Most financial guides seemed to be written for middle-aged readers with millions in assets, rather than recent college grads. "I was reading every book I could find, but none of them spoke to me," she says. So she came up with the idea for LearnVest, an online personal-finance resource for young women like her, and ended up writing an 80-page business plan.


After two years at Morgan Stanley, von Tobel entered Harvard Business School in 2008. But upon winning a business plan competition held by Astia, a non-profit that supports women entrepreneurs, she took a five-year leave of absence and invested $75,000 of her Wall Street earnings to start LearnVest in November. She quickly enlisted advisors, including Betsy Morgan, the former CEO of the Huffington Post, and Catherine Levene, the former COO of DailyCandy, to help develop the site’s content and technology. In January 2009, she secured $1.1 million in seed funding from executives at Goldman Sachs.


LearnVest’s site launched a year later and has since signed up more than 100,000 members. It offers online budgeting calculators, video chats with certified financial planners on the company’s staff, and free e-mail tutorials on topics such as opening an IRA. The company earns revenue from advertising and by referring its users to companies such as TD Ameritrade. In April, after just four weeks of fundraising, von Tobel closed a $4.5 million investment round led by Accel Partners, which has also invested in Facebook and Etsy. (Incidentally, Facebook CEO Mark Zuckerberg lived in the same dorm as von Tobel at Harvard.)


Von Tobel likens LearnVest to an online version of The Suze Orman Show, but with the goal of reinforcing positive finance habits early on. “Suze Orman helps 45-year-old women get out of debt,” she says. “Why not reach 20-year-olds to keep them from getting into debt?”


internet marketing course

Learning how to control personal finance is empowering and rewarding. When debt controls your life and leaves you reaching for credit cards to buy a pack of gum, it is time to take a serious look at your financial situation. Most people are overwhelmed by the thought of creating a budget, but doing so is the only avenue to financial freedom.

Regardless of the severity of personal finance problems, there is always a solution. The first step to regaining control is to thoroughly review expenses and spending habits. Start by making a list of living expenses including rent or mortgage payments, utilities, cell phone, car payments, home, auto and life insurance, daycare, and groceries. Next, total up your net household income and subtract the expenses. If you spend more than you earn, it's time to make budget cuts or increase income.

Budgeting is most affordable way to get finances back on track. The only tools required are a pencil and piece of paper, along with a commitment to track every dime spent. Most banks offer budgeting software which can be useful in recording daily expenses. Some people prefer to purchase budgeting software or create spreadsheets. It doesn't matter which method is used, but choose the one which you are most likely to use on a consistent basis.

With a bit of creativity and a few phones, you can potentially slash expenses by up to 50-percent. Utility companies generally offer budget plans that allow customers to pay the same amount each month. This is particularly helpful during winter and summer months when utility bills can soar. Enrolling in utility budget plans can be accomplished by contacting the company by phone or visiting their website. Most utility companies offer online enrollment options.

Another place to reduce expenses is through negotiating with cable and internet providers. In order to be successful, you will need to take time to comparison shop and determine competitor prices.

Contact providers by phone and explain that company ABC offers the same package you are currently subscribed to for x-amount of dollars. Many service providers offer deeply discounted deals for new subscribers, so be certain to find out what packages are available through your current provider. Most cable and internet providers will reduce rates to keep your business. If they aren't willing to offer a better price, consider switching to a reduced price plan or obtain service through a different provider.

Groceries can quickly eat away your budget, but savvy shoppers know the power of manufacturer coupons. Thanks to the Internet, it has never been easier to save money at the grocery store. Many manufacturers offer coupons and rebates directly from their websites. There are websites dedicated to providing coupons that can be printed from the comfort of home.

Some people believe that clipping coupons is time-consuming and not worth the effort. Nothing could be further from the truth. I know a woman who saves up to 90-percent off her weekly grocery bill simply by clipping coupons.

If you spend $400 per month at the grocery store and can slash 30-percent from your bill, that's $120 in your pocket. Saving that money might take two hours of time to clip grocery coupons. Over the course of a year you could save $1440 or enough for a nice vacation.

In order to get out of debt, you must know where every penny is spent. Taking time to record expenses on a piece of paper can help you quickly determine what is depleting your bank account. I once knew a man who wasted $4500 per year buying bottled water and morning lattes. Since he was purchasing these items one at a time, he didn't realize how much money he was spending on liquid items. How much of your personal finance is being flushed down the toilet? Track your expenses for a month to find out.

Perhaps the biggest source of financial problems stems from credit card debt. If you are near your limit and barely making minimum payments consider obtaining credit card debt relief assistance.

Many companies offer debt solutions such as debt consolidation and debt settlement. It is important to conduct research and shop around for the best deal. Debt help companies typically charge a start-up and monthly fee.

If debts have spiraled out of control and debt collectors are hounding you day and night, consider obtaining credit counseling. Credit counselors can help individuals regain control of personal finance through time-tested personal money management strategies.


penis enlargement

Arrowheadlines: Chiefs <b>News</b> 7/19 - Arrowhead Pride

Welcome to another week. Your Kansas City Chiefs news waits below. Not too much today. Enjoy.

BREAKING <b>NEWS</b>: Pettitte out 4-5 weeks; Mitre to start Saturday <b>...</b>

According to Brian Cashman via Chad Jennings, Andy Pettitte will be placed on the DL and could be out for 4-5 weeks. He will be replaced in the starting.

Bob Schieffer Defends Himself Against Fox <b>News</b> On New Black <b>...</b>

CBS News' Bob Schieffer defended himself against Fox News Sunday on CNN's "Reliable Sources." Schieffer, who interviewed Attorney General Eric Holder last weekend on "Face the Nation," came under fire from Fox News' Megyn Kelly for not ...


how to lose weight fast


Thursday, July 15, 2010

bank foreclosure


Foreclosure Mediation Programs Succeed Across The Country — Will Pawlenty Give Minnesota’s A Chance?


Today, across the country, mortgage mediation programs aimed at helping struggling homeowners stay in their homes are getting underway. Programs are launching in Maryland, as well as Florida’s 6th and 10th judicial circuits — encompassing Pasco, Pinellas, Hardee, Highlands, and Polk counties — while Cook County, Illinois is beginning a huge round of outreach for its burgeoning program.


In all, “the number of jurisdictions with foreclosure mediation programs is nearly double the number a year ago, with jurisdictions in 21 states now offering foreclosure mediation or negotiation programs.” Not on this list, however, is Minnesota, where Gov. Tim Pawlenty (R) saw fit to veto a program last year.


The Minnesota state senate recently passed the bill again, sending it to the state House, so Pawlenty could very well get a second shot soon. And there’s simply no reason for him to oppose the program, as mediation — during which a bank meets face-to-face with a borrower, often in the presence of a judge and housing advocates, to try and forge a mortgage modification or other arrangement that prevents a foreclosure — is one of the most successful methods of helping struggling borrowers stay in their homes.


Connecticut’s mediation program, for instance, has kept 60 percent of its borrowers out of foreclosure. Philadelphia’s success rate is also 60 percent, while Nevada claims an 85 percent success rate:


About 80 percent of homeowners at risk of losing their homes don’t engage in any efforts to negotiate with their lender. And those who do so on their own often run into a bureaucratic mess, including hours on hold, lost records, and customer service representatives who know nothing about the borrower’s situation. Mediation helps to ensure that situations like that don’t happen.


“These new protections empower our fellow Marylanders, putting them on a more equal footing with mortgage companies that too often can’t be bothered to pick up the phone before beginning a foreclosure proceeding against a Maryland family,” said Governor Martin O’Malley (D). And lest Pawlenty think this is a purely partisan issue, it has also won the praise of Gov. Jodi Rell (R-CT). “Clearly, mediation is an effective tool homeowners can use to ward off foreclosure,” she said. “This program is a beacon of hope for hard-pressed homeowners and a real alternative for lenders.”


In mediation, there’s no requirement for a lender to accommodate a borrower, but it’s often the case that preventing a foreclosure is in the best financial interest of both the borrower and the lender. As CAP’s Andrew Jakabovics and Alon Cohen wrote, “the simple act of participating in mediation consistently yields solutions short of foreclosure that are acceptable to both sides.” Hopefully, should the Minnesota legislature do the right thing and create a program, Pawlenty will allow it to stand.


Slightly more than one out of three homes sold in Kootenai County during the first quarter of 2010 was in foreclosure or already bank-owned, according to RealtyTrac.

The 182 homes sold was more than triple the number sold out of or after foreclosure in the first quarter of 2009, and 50 percent more than the fourth-quarter 2009 sales, said RealtyTrac, which tracks foreclosure activity nationally.

But the average foreclosure price, at $194,639, was an increase from the $184,707 for the last quarter of 2009, and the $169,472 for the first quarter. Foreclosed homes sold at less than a 5 percent …


distraction


BREAKING <b>NEWS</b>: Joseph Lacob and Peter Guber outbid Larry Ellison <b>...</b>

The word is that the new owner of the Golden State Warriors is NOT Larry Ellison, but Joseph Lacob and Peter Guber.

BBC - BBC Internet Blog: BBC <b>News</b> website redesign: telling the story

A place where senior staff from the BBC's Future Media and Technology teams, will discuss issues raised by you about BBC Online, the BBC's digital and mobile services, and the technology behind them.

Lebanon arrests another telecom worker for spying - Arab <b>News</b>

At no time will Arab News attempt to alter the core meaning of a comment. 3. Reject the message, edit the message when the moderators judge it to be a personal attack, defamatory (or potentially defamatory), abusive, incite hatred or ...


Wednesday, July 14, 2010

1 internet marketing


There’s a reason Prince made it onto Time’s 100 Most Influential Celebrities list.  His musical legacy is easily apparent, and his opinions are still making headlines.  Recently, the purple-clad eccentric has endured great scorn for his statement, “The Internet’s completely over.”  Just so you know he’s serious, Prince has banned his music from YouTube and iTunes, shut down his own website, and announced his newest album 20TEN will only be distributed as a free CD inside the British paper the Daily Mirror (much to the chagrin of my wife and sis-in-law, huge fans).


After blasting online music distributors, Prince calls the technology itself a fad that’s on the way out:  “The Internet’s like MTV.  At one time MTV was hip and suddenly it became outdated. Anyway, all these computers and digital gadgets are no good.”  Obviously, he’s out of touch; MTV was a diversion, not a tool that expanded the potential accomplishments of virtually every business and individual in the world.   Nor were millions of people physically addicted to MTV and its content.


 Though his statement is demonstrably false, there’s something to the sentiment behind it.  I’ve rarely bought mp3s online that I could buy on a physical format for two reasons:  first, lower sound quality (to bring the file sizes down, they remove frequencies and decrease the audio’s resolution), and I prefer the limitation of having to choose and listen to one CD at a time.  Just browsing through a collection of mp3s ripped from the same CDs, I appall myself, getting so easily bored and skipping through music that I find exhilarating when I commit to it.  Despite an age difference of three decades, Prince and I find solidarity in this anachronism.


But aside from personal taste, the problem with online mp3s is that the music industry has long been plagued by piracy– much more than TV or film due to smaller file sizes.  Despite the option of cheap, convenient, buffet-style digital music stores, pirates are still ubiquitous, and they cost record labels serious money.


For those conservatives not familiar with the concept of receiving a good or service without paying for it, online piracy is the unholy union of the West’s appalling entitlement mentality, anti-corporate zealotry, and a warped sense of economic progress.  For the uninitiated, here is a list of what I’ve dubbed the Six Levels of Piracy:


Level 1:   Listening to burned CDs from friends (technically illegal, but akin to the virtuous Before Christ residents of Dante’s Inferno)


Level 2:  Downloading mp3s from music blogs which host songs without permission from artists


Level 3:  Paying for a Rapidshare Premium account but not paying for music


Level 4:  Downloading torrents


Level 5:  Leaking content onto torrent sites


Level 6:  Openly promoting piracy


What online pirates (generally anti-corporation leftists) fail to realize is that music distribution, like any business, has costs that need to be made up when selling its product:  payroll for songwriters, artists, producers, and recording engineers who actually make the music; manufacturing, packaging, and shipping CDs; promotion, marketing, and expensive ads called music videos; plus administrative and legal costs and taxes (most labels are international and have to pay European VAT taxes).  Then, retailers buy the music and have to sell it at a higher price to cover their own costs and make a profit (profit is how these people stay in business and make sure we can still have music in the future).


Artists such as 9 Inch Nails’ Trent Reznor have fueled pirates’ costless fantasy world, lamenting,


“Wait – you sell for $18.98 and I make 80 cents? And I have to pay you back the money you lent me to make it and then you own it? Who the f**k made that rule? Oh! The record labels made it because artists are dumb and they’ll sign anything.”  


In response, let’s think up a little analogy that progressives like Mr. Reznor can understand.  If the benevolent feds charge NASA with building a new shuttle that will collect tons of pure gold on a distant planet, the astronaut who pilots the shuttle will not receive the majority of the gold.  Congress funded the building of the ship. They authorized the mission. They took the financial risk, so they will reap the majority of the financial reward. The astronaut will still get copious amounts of money; it’s just that most will be from the speaking tour after the mission. 


Regardless, Reznor and fellow ‘90s sensations Radiohead have tried a novel idea—allowing customers to set their own price for albums. In 2007, Radiohead released a self-produced album, In Rainbows, and before it hit stores, anyone could log onto their website and type in how much they would pay for the twelve tracks.  I’ll admit that I paid nothing, mostly because I find Radiohead disgustingly overrated.  The band hasn’t released any sales figures for the experiment, but they’ve said they won’t do it again. 


For bands such as Radiohead, their established fan base (which exists largely because of the evil music industry corporations) can potentially make this donation-based distribution work.  It may also work for smaller indie bands that have low production costs.  But for developing artists trying to go national, a small core of rabid, paying fans likely won’t be able to cover the costs of ambitious, professional recordings, so I doubt that many will adopt In Rainbows’ strategy.  Sites with free song streaming plus ads, such as Grooveshark.com, show potential also, but between the Wall Street Journal, Hulu, and (allegedly) MySpace deciding to adopt subscription-based services for online content, this business model might only yield the results of Keynesianism in time.


Therefore, what Prince says may be true to a point.  Digital distribution of music could end up a bust; that may be the reason that sales of vinyl records are on the rise.  It’s certainly a much more credible assertion than Radiohead’s Thom Yorke predicting that the entire music industry will collapse within “months” (he gets a pass from the press, cuz he’s a courageous crusader against climate change).  Regardless, it’s good to see such a bizarre, entertaining character—read the whole interview; you’ll thank me—retain some semblance of free thought instead of slipping into leftist orthodoxy after so many years in the music business.


Viacom v Internet: round one to Internet


Google's won the first round of the enormous lawsuit Viacom brought against it. Viacom is suing Google for $1 billion for not having copyright lawyers inspect all the videos that get uploaded to YouTube before they're made live (they're also asking that Google eliminate private videos because these movies -- often of personal moments in YouTubers' lives -- can't be inspected by Viacom's copyright enforcers).


The lawsuit has been a circus. Filings in the case reveal that Viacom paid dozens of marketing companies to clandestinely upload its videos to YouTube (sometimes "roughing them up" to make them look like pirate-chic leaks). Viacom uploaded so much of its content to YouTube that it actually lost track of which videos were "really" pirated, and which ones it had put there, and sent legal threats to Google over videos it had placed itself.


Other filings reveal profanity-laced email exchanges between different Viacom execs debating who will get to run YouTube when Viacom destroys it with lawsuits, and execs who express their desire to sue YouTube because they can't afford to buy the company and can't replicate its success on their own.


On Wednesday, U.S. District Judge Louis Stanton ruled that YouTube was protected from liability for copyright infringement by the 1998 Digital Millennium Copyright Act (DMCA). The DMCA has a "safe harbor" provision that exempts service providers from copyright liability if they expeditiously remove material on notice that it is infringing. Viacom's unique interpretation of this statute held that online service providers should review all material before it went live. If they're right, you can kiss every message-board, Twitter-feed, photo-hosting service, and blogging platform goodbye -- even if it was worth someone's time to pay a lawyer $500/hour to look at Twitter and approve tweets before they went live, there just aren't enough lawyers in the universe to scratch the surface of these surfaces. For example, YouTube alone gets over 29 hours' worth of video per minute.


Viacom has vowed to appeal.


In dismissing the lawsuit before a trial, Stanton noted that Viacom had spent several months accumulating about 100,000 videos violating its copyright and then sent a mass takedown notice on Feb. 2, 2007. By the next business day, Stanton said, YouTube had removed virtually all of them.


Stanton said there's no dispute that "when YouTube was given the (takedown) notices, it removed the material."


Calling Stanton's reasoning "fundamentally flawed," Viacom said it was looking forward to challenging the decision in appeals court.


Judge sides with Google in $1B Viacom lawsuit
(Thanks, Mike P!)


(Image: Viacom, a Creative Commons Attribution Non-Commercial Share-Alike (2.0) image from mag3737's photostream -- used with permission)

online stock trading online stock trading

Probably Bad <b>News</b>: Kids Meal Toy Fail - FAIL Blog: Epic Fail Funny <b>...</b>

Actually, this was reported multiple times over. The Mexican newspaper El Universal Mexico ran the story, and the Los Angeles TV station Univision (channel 34) also ran it – both of them as truth. El Universal even “quoted” CAP News. ...

Early Market <b>News</b>: Apple Inc. (NASDAQ:AAPL), Google Inc. (NASDAQ <b>...</b>

Several breaking news stories will affect stock prices when trading continues. The following companies should see some movement: Apple Inc. (NASDAQ:AAPL), Google Inc. (NASDAQ:GOOG) and Citigroup Inc. (NYSE:C). ...

Fox <b>News</b> launches Android app – Android and Me

If you are a fan of Fox News, accessing all their shows and content just got a lot easier with the release of their new Android app. Fox News rates as the United States' most watched cable news channel and their first attempt at Android ...


Friday, July 9, 2010

Buying Investments Online


Roundup, deals, VC


RevenueLoan Pushes New Funding Model, Tippr Expands in Group Buying, Microsoft and Google Lure Startups, & More Seattle-Area Deals News


Gregory T. Huang 6/8/10

OK, things have started to pick up in terms of deals news around the Northwest. This week was headlined by the activities of a trio of well-known characters in the Seattle tech scene.


—Xconomy had an exclusive in-depth interview with entrepreneur Andy Sack about his new company, RevenueLoan, which has raised $6 million from Voyager Capital, Summit Capital, and Founder’s Co-op. The idea is to make “revenue-based” investments in mostly tech startups. That means instead of taking an equity stake in a company, RevenueLoan will get paid a percentage of the company’s future revenues up to a certain multiplier of its investment (typically 3-5x). I first wrote about this investment model, and how it could shake up the VC ecosystem, last fall.


—Seattle-based BigDoor Media, the Internet startup run by Keith Smith and Jeff Malek, raised $5 million in Series B funding led by Boulder, CO-based Foundry Group. BigDoor has developed a software platform that lets Web publishers add videogame-like mechanics to their sites—things like reward points, leader boards, and virtual goods and currencies—with the goal of boosting traffic and revenues. It’s all part of an increasing trend towards “gamification” of the Web, as led by companies like Zynga and Foursquare.


—Seattle-based Tippr.com, the online group-buying site led by Martin Tobias, acquired Chitown Deals, based in Chicago, for an undisclosed amount. Tippr is now active in 10 cities around the U.S. including Chicago, the hometown of deal-of-the-day giant Groupon. Tippr rolled out its website in February, after acquiring the patent portfolio of Mercata, a former dot-com backed by Paul Allen’s Vulcan Capital.


—Not exactly deals per se, but it’s interesting to note that Microsoft and Google are appealing to tech startups and developers in new ways. Bing Maps is providing a software development kit for startups to build location-based applications on top of its maps. Meanwhile, the Google Apps Marketplace added another Seattle-area company’s software to its list of offerings. Napera Networks, which makes network management and security software for businesses, earned that distincition from Google.


Gregory T. Huang is Xconomy's National IT Editor and the Editor of Xconomy Boston. You can e-mail him at gthuang@xconomy.com, call 206-624-2249, or follow him at twitter.com/gthuang.


Roundup, deals, VC


RevenueLoan Pushes New Funding Model, Tippr Expands in Group Buying, Microsoft and Google Lure Startups, & More Seattle-Area Deals News


Gregory T. Huang 6/8/10

OK, things have started to pick up in terms of deals news around the Northwest. This week was headlined by the activities of a trio of well-known characters in the Seattle tech scene.


—Xconomy had an exclusive in-depth interview with entrepreneur Andy Sack about his new company, RevenueLoan, which has raised $6 million from Voyager Capital, Summit Capital, and Founder’s Co-op. The idea is to make “revenue-based” investments in mostly tech startups. That means instead of taking an equity stake in a company, RevenueLoan will get paid a percentage of the company’s future revenues up to a certain multiplier of its investment (typically 3-5x). I first wrote about this investment model, and how it could shake up the VC ecosystem, last fall.


—Seattle-based BigDoor Media, the Internet startup run by Keith Smith and Jeff Malek, raised $5 million in Series B funding led by Boulder, CO-based Foundry Group. BigDoor has developed a software platform that lets Web publishers add videogame-like mechanics to their sites—things like reward points, leader boards, and virtual goods and currencies—with the goal of boosting traffic and revenues. It’s all part of an increasing trend towards “gamification” of the Web, as led by companies like Zynga and Foursquare.


—Seattle-based Tippr.com, the online group-buying site led by Martin Tobias, acquired Chitown Deals, based in Chicago, for an undisclosed amount. Tippr is now active in 10 cities around the U.S. including Chicago, the hometown of deal-of-the-day giant Groupon. Tippr rolled out its website in February, after acquiring the patent portfolio of Mercata, a former dot-com backed by Paul Allen’s Vulcan Capital.


—Not exactly deals per se, but it’s interesting to note that Microsoft and Google are appealing to tech startups and developers in new ways. Bing Maps is providing a software development kit for startups to build location-based applications on top of its maps. Meanwhile, the Google Apps Marketplace added another Seattle-area company’s software to its list of offerings. Napera Networks, which makes network management and security software for businesses, earned that distincition from Google.


Gregory T. Huang is Xconomy's National IT Editor and the Editor of Xconomy Boston. You can e-mail him at gthuang@xconomy.com, call 206-624-2249, or follow him at twitter.com/gthuang.


Mike Fuljenz Mike Fuljenz

dot patchwork landscape by Kasarn Designs


Friday, July 2, 2010

foreclosure homes


BofA executive Jack Schakett made some interesting comments earlier today:

"There is a huge incentive for customers to walk away because getting free rent and waiting out foreclosure can be very appealing to customers."
Schakett noted that the foreclosure process is currently taking 13 to 14 months ...

For many the timeframe is apparently much longer. On Monday David Streitfeld wrote in the NY Times: Owners Stop Paying Mortgages, and Stop Fretting
The average borrower in foreclosure has been delinquent for 438 days before actually being evicted, up from 251 days in January 2008, according to LPS Applied Analytics.
...
More than 650,000 households had not paid in 18 months, LPS calculated earlier this year. With 19 percent of those homes, the lender had not even begun to take action to repossess the property ...
These long foreclosure time lines can have a significant adverse impact on housing.

Housing economist Tom Lawler alerted me to a 2008 research paper by Freddie Mac economists Amy Crews Cutts and William A. Merrill: Interventions in Mortgage Default: Policies and Practices to Prevent Home Loss and Lower Costs. They studied the foreclosure time lines and costs in several states and found that 270 days is sufficient time to allow the borrower to cure, and any more time actually incentivizes the borrower to strategically default:
There are many challenges that policy makers, investors, servicers and borrowers face in minimizing the incidence of home loss through foreclosure. Among them is the tension between too little time in the foreclosure process, such that some borrowers are unable to recover from relatively mild setbacks before they lose the home but investors minimize pre-foreclosure time related costs, and too much time in the foreclosure process, such that the borrower is incented to let the home go to foreclosure sale during which no mortgage payments are made (in essence, free rent for a significant time) and investor costs rise rapidly.
...
A sweet spot for the optimal time in foreclosure likely exists around a statutory timeline of 120 days (the current national median, and equivalent to 270 days after adding in 150 days for pre-referral loss mitigation activities by servicers through workouts) in which the borrower’s incentives are aligned with both a high probability of curing out of the foreclosure and keeping the pre-foreclosure costs to the investor contained.
One of unintended consequences of the government foreclosure delaying strategy (probably aimed at limiting supply and supporting house prices), is that strategic defaults have gained fairly widespread acceptance. And that means the eventual cost to the taxpayer will be higher than if the lenders had either modified the loans, or foreclosed, or approved a short sale, within about 270 days.


Foreclosure Mediation Programs Succeed Across The Country — Will Pawlenty Give Minnesota’s A Chance?


Today, across the country, mortgage mediation programs aimed at helping struggling homeowners stay in their homes are getting underway. Programs are launching in Maryland, as well as Florida’s 6th and 10th judicial circuits — encompassing Pasco, Pinellas, Hardee, Highlands, and Polk counties — while Cook County, Illinois is beginning a huge round of outreach for its burgeoning program.


In all, “the number of jurisdictions with foreclosure mediation programs is nearly double the number a year ago, with jurisdictions in 21 states now offering foreclosure mediation or negotiation programs.” Not on this list, however, is Minnesota, where Gov. Tim Pawlenty (R) saw fit to veto a program last year.


The Minnesota state senate recently passed the bill again, sending it to the state House, so Pawlenty could very well get a second shot soon. And there’s simply no reason for him to oppose the program, as mediation — during which a bank meets face-to-face with a borrower, often in the presence of a judge and housing advocates, to try and forge a mortgage modification or other arrangement that prevents a foreclosure — is one of the most successful methods of helping struggling borrowers stay in their homes.


Connecticut’s mediation program, for instance, has kept 60 percent of its borrowers out of foreclosure. Philadelphia’s success rate is also 60 percent, while Nevada claims an 85 percent success rate:


About 80 percent of homeowners at risk of losing their homes don’t engage in any efforts to negotiate with their lender. And those who do so on their own often run into a bureaucratic mess, including hours on hold, lost records, and customer service representatives who know nothing about the borrower’s situation. Mediation helps to ensure that situations like that don’t happen.


“These new protections empower our fellow Marylanders, putting them on a more equal footing with mortgage companies that too often can’t be bothered to pick up the phone before beginning a foreclosure proceeding against a Maryland family,” said Governor Martin O’Malley (D). And lest Pawlenty think this is a purely partisan issue, it has also won the praise of Gov. Jodi Rell (R-CT). “Clearly, mediation is an effective tool homeowners can use to ward off foreclosure,” she said. “This program is a beacon of hope for hard-pressed homeowners and a real alternative for lenders.”


In mediation, there’s no requirement for a lender to accommodate a borrower, but it’s often the case that preventing a foreclosure is in the best financial interest of both the borrower and the lender. As CAP’s Andrew Jakabovics and Alon Cohen wrote, “the simple act of participating in mediation consistently yields solutions short of foreclosure that are acceptable to both sides.” Hopefully, should the Minnesota legislature do the right thing and create a program, Pawlenty will allow it to stand.


penis enlargement products

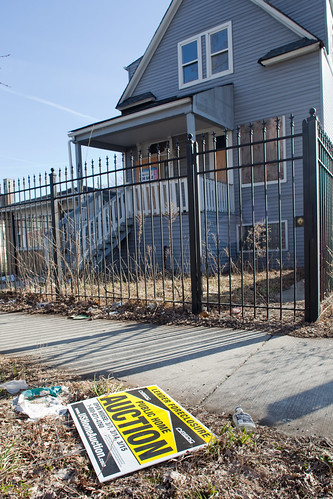
Increasingly Common: Lender Foreclosure Public Home Auction by metroblossom

Monday, June 21, 2010

personal finance money management


Save Money by Establishing Passive Spending Barriers


If you're looking to save money—and who isn't?—good money habits go a long way towards keeping cash in your checking account. Establish passive spending barriers to keep spending in check.

Adam Baker, over at the financial blog Get Rich Slowly, decided the best way to keep money in his pocket was to set up passive barriers that worked for him instead of against him which made it easy to keep with them until they became a habit. For those of you behind The Great Corporate Firewall, you can check out the contents of the video via the list below:


  1. The 30-day list for Wants -

  2. Two items out for every item in -

  3. Experiences over possessions -


I have a strong appreciation for the last two. I'm at the age now where the majority of my friends have purchased homes and have accumulated a bunch of stuff. I'm actively decluttering my home and office every day to pare down the stuff I already have and I feel almost hypocritical piling more stuff on somebody else as a gift. Lately I've been much more likely to give something to a friend that they can experience—theater tickets, a bottle of wine, taking their kids to the park so they can have dinner with adult conversation, etc.—than I am to give them something they have to dust and put a roof over. You can read more about the idea of giving experiences here.


Have a tip or trick that you'd add to the list above? Let's hear about it in the comments.


A recent study found that poor folks - households earning under $13,000 per year - spend about 9% of all their income on lottery tickets.


Jonah Lehrer:

The study neatly illuminates the sad positive feedback loop of lotteries. The games naturally appeal to poor people, which causes them to spend disproportionate amounts of their income on lotteries, which helps keep them poor, which keeps them buying tickets.
I wonder what would happen if on a certain number of the losing scratch-off cards, scratching off the latex ink won you free personal finance and budget management services.


Lotteries [The Frontal Cortex] (Thanks to Jim!)

The impact of narrow decision bracketing on lottery play [Journal of Risk and Uncertainty]


penis enlargement

The most important factor of growing up is learning how to manage our money. Chilton (1998) claims that most of us learn money management from our parents along with their values, beliefs, spending habits, and how much they share and teach us about money. Even though most of us listen to and follow the fundamentals our parents instilled in us, we still develop our own values, beliefs, and habits. As we gain our own ideas, and learn an understanding of personal finance we can develop a plan to benefit from proper financial planning.

Financial planning is an essential element to personal finance by setting up goals and a path to meet your goals creating that personal freedom for those who strive for it. Financial planning consists of budgeting, savings and investing in your future. A strong budget allows managing your money to include savings and investing. The key step in knowing how important savings is in a financial plan is you can go far with out it. Without savings you can't accumulate enough capital to invest, or if something were to happen you may have to cash in valuable investment with a huge loss due to unexpected emergencies.
A financial plan specifies your financial goals and sets a path to achieve those goals. With a good understanding of personal finance you have the ability to make your own financial decisions. A good understanding allows you to judge and give yourself sound financial advice. The whole idea of Chilton's novel, "The Wealthy Barber", is to save money now and live better in the future. By making sound financial decisions you can create wealth for the present and well into your retirement and after.

A few benefits of understanding personal finance are being able to protect your assets and income. If something terrible were to happen to yourself or your spouse, the right planning and the knowledge of having the proper insurance is all you need to protect yourself and your family. Knowing how to invest in stocks, bonds, mutual funds, and real estate can produce a substantial return to benefit you in the future. The right understanding allows you to minimize risk and maximize returns. The proper understanding of how to save and invest can lead to accumulate sufficient money to support yourself after you retire.

A true understanding of personal finance allows us to buy the best house for our family, put our children through college, and retire young enough to enjoy the remainder of lives with our loved ones. Getting a financial advisor without the proper understanding where your money is going can be very dangerous. Your ignorance can lead to someone taking advantage of you and your money, which could cause you to lose your entire nest egg. An understanding of how to manage our money, assets, and investments is our responsibility and we can reap the benefits in the long run. When it comes to personal finances "people are reluctant to discuss personal finances outside the family circle, except with financial advisors-bank managers, solicitors, accountants - whose professional standing provides an assurance of confidentiality." (Aldridge, 1998: pg.8)

Usually one does not talk about savings with their financial advisor, because it's always about what are the best funds or stocks to increase their net present value. It is essential to know how much to save and how to make it work for you. Savings can be viewed as short-term goals or long-term goals. A short-term goal is saving extra money for a short period of time for a major purchase, like a down payment on a house or car, possibly a household renovation. These types of items that you would normally save for minimize your payments or avoid an interest bearing loan. Long-term savings goals are plans to have readily available cash at hand, with no plans on spending it unless of an emergency. It's a long-term savings because you can maintain it until you retire and it continually builds dividends. A common long-term savings goals is an emergency fund that should consist of a minimum six months worth of salaries and if able up to a full years salaries. In addition to an emergency fund a sound financial plan should have money allocated to another savings account on a monthly basis.

Credit management is important because you can't survive without it. It's important to consider you can't buy a house, a car, or get a credit card without some kind of credit history. Credit management begins with your first bank account and doesn't end until you die and in some cases it can out live you. You start to establish history with every dollar you save and spend. Starting off right is the first step to establishing a good credit history. You have to manage your credit by paying your debts on time. The better your credit gets the more creditors want to give you and this can be trouble. Your one credit card turns into five cards, as a result you then have a new car loan, and you're using your credit cards to pay other cards and your car payment.

This is a typical situation with inexperienced people who do not know anything about credit. It's very common for a family to go out for a night on the town and take a credit card. A credit card may carry a fee, and also a risk of theft and forgery, but it is very convenient and the free credit period allows money to be held temporarily in a form earning more than a bank account. (Robinson/McGoun 1998).The convenience and safety of credit cards offer you just can't get with cash. Credit cards are the most used form of credit and have the potential to be misused. If you misuse credit it usually will takes years to recover and you have established a bad credit history. Tyson (2006) recommends that you "get all three of your credit card reports, and be sure each is accurate".

In addition to credit cards you have various types of loans. You have personal loans, car loans, house loans and school loans which all build your credit history. Credit management affects what kind of loan you have available and the terms of the loan. With bad credit, loans have a higher interest rate and they can take longer to pay off. Once you learn good credit management you can use it to your advantage in financial planning. Wisely choosing the best loans and terms of your choice vise the creditors is an advantage. When doing your financial planning, the amount of credit you can afford to have is very important because it can lay the framework to a successful financial future.

Buying a home may be the single biggest investment you will ever make, so the decision should be taken very seriously. As claimed by Chilton (1998) it is said that about ninety percent of the world's millionaires have become millionaires through real estate. (pg. 60) With that said not everyone is ready to buy a house. When it comes down to it the decision is it better to buy a home or rent? In addition Barnes/Jaret (2003) states achieving the "American Dream" has often been associated with living in a thrifty manner, accumulating savings, and subsequently purchasing a home of one's own, which then appreciates in value and becomes a large component of one's personal wealth. When it comes to purchasing a home there are a lot of factors to be considered.

First the larger the down payment the better chance you have of getting the home you want. You need a house to meet your needs and a house you can afford. A house provides security and it represents your own little piece of that "American Dream". Every month that you pay into that a house you can say you own just a little bit more of that dream. With a little luck as the years go by, your house appreciates in value. Once you pay it off or sell you can feel like you made a difference in someone's life, to include your own. A down side of owning a home is you can tie yourself to a location and into a deal that you can't get out of easily. "Patience is always one of the most valuable attributes in investing, and nowhere is that more true then in real estate. It may go down, but it seldom stays there indefinitely." (Chilton pg. 62)

Determining the amount of life insurance is the most important in financial planning because the amount can focus the way you chose insurance. There are two methods of determining how much life insurance is needed. The first income method is a general formula for determining how much insurance based off your income. The income method suggests you multiply your annual income by ten. This is a straight line method that doesn't take into account a single person salary vise a family of four which will require more life insurance. The second method is a budgeting method, which determines your life insurance needs by considering your future budget based on your household's future expected expenses and your current financial situation.

The budgeting method takes into account your annual living expenses, special future expenses, debt, the job marketability of your spouse, and the value of your savings. Robinson (1998) highlights, in budgeting, we treat all sources of income identically and add them up. However, a formal model based on some theory of smoothing lifetime income and consumption would allocate a large part of any windfall into savings rather than expenditures. Once you have established the amount you need for life insurance, you have to consider what kind of life insurance that best suits your needs. When it comes to your financial plan, investing is an intricate part in securing your future. Money management is about short-term and long-term planning, and having a nice size nest egg, as you get closer to retirement.

Chilton (1998) recommends to not throwing all your eggs in one basket. To avoid living pay check-to-pay check, we have to plan and learn to invest in our future. In today's market you have so many choices that you can invest in. Depending on your willingness to take risks and where you want your money will set the basis for you individual investment portfolio. Some of the most common types of investments are IRA's, Stocks, and Bonds; each type of investment has its advantages and disadvantages.

Chilton (1998) recommends indulging in the stock market. Stocks are very popular and can be a risky investment and can produce a larger return or break you over night. A stock is a certificate of partial ownership of a firm. With the Internet, the option of buying stocks is easier than ever and has introduced new opportunities to an individual investor. It uses to be that you had to look for professional help but now it a few clicks away. Stocks are riskier investments but yield higher returns. Common stock is basic stock sometimes giving you rights to vote and elect board members who will run the company. Preferred stock guarantees you to receive dividends over the common stockholders. The downsides to stocks are the price of stocks can drop and you can lose an entire investment.

Another way to make yourself more financial set is to watch your spending as sated by Tyson (2006). Tyson recommends reducing spending in order to become more financially set. Simple ways to avoid spending money are as simple as using public transportation, using regular unleaded gas and servicing your car. Also it is important to avoid buying clothes that require dry cleaning, not indulging in the latest season's fashions and to keep accessories to a bare minimum.

No matter how you decide to save money and invest money, it should be made to fit as part as your financial plan. Both Chilton and Tyson make very good points about spending and saving, what to invest your money into and what not to. I have learned a lot about my personal finances through reading these two books. I found that Chilton's book was more of a story and more personal, then Tyson's to-the-point facts about finance. Out of the two books I think that I learned more from Tyson's, but both were enjoyed. Also both books made me realize that really I am investing in myself and my future.

References:
-Aldridge, Alan (1998) "Habitus and cultural capital in the field of personal finance." University of Nottingham

-Barnes, S & Jaret, C. (2003) Sociological focus The "American Dream" in poor urban neighborhoods: An analysis of home ownership attitudes and behaviors and financial saving behavior. Purdue University and Georgia State University

-Chilton, David. (1998) The Wealthy Barber. Roseville, CA: Prima Publishing.

-Gill, Suveera (2005) An Analysis of defaults of Long-term Rated Debts, Vikalpa volume 30

-Robinson, Chris and McGoun, Elton (1998) The sociology of personal finance. Financial Services Review 7

-Sandlin, Jennifer (2005) Culture, Consumption and Adult Education: Education for adults as a political site using a cultural studies framework. Texas A&M University

-Tyson, Eric. (2006) Personal Finance for Dummies 5th Ed. Hoboken, NJ. Wiley Publishing, Inc.


Knight <b>News</b> Challenge: GoMap Riga won&#39;t make much new, just <b>...</b>

The lines between news, civic engagement, and crowdsourcing blur for one of the 2010 Knight News Challenge winners. A project called GoMap Riga wants to build a.

Toshiba unveiled their Android 2.1-based netbook, the Dynabook AZ <b>...</b>

Dannychoo.com – Your portal to Japan (Subscribe); - Japan Probe – News from Japan (Subscribe). < < Previous Post .... Welcome to Akihabara News V5.5 a.k.a “Access Denied €... Sony Develops a "Rollable" OTFT-driven OLED Display tha. ...

Facebook update adds video support | iLounge <b>News</b>

iLounge news discussing the Facebook update adds video support. Find more Apps + Games news from leading independent iPod, iPhone, and iPad site.